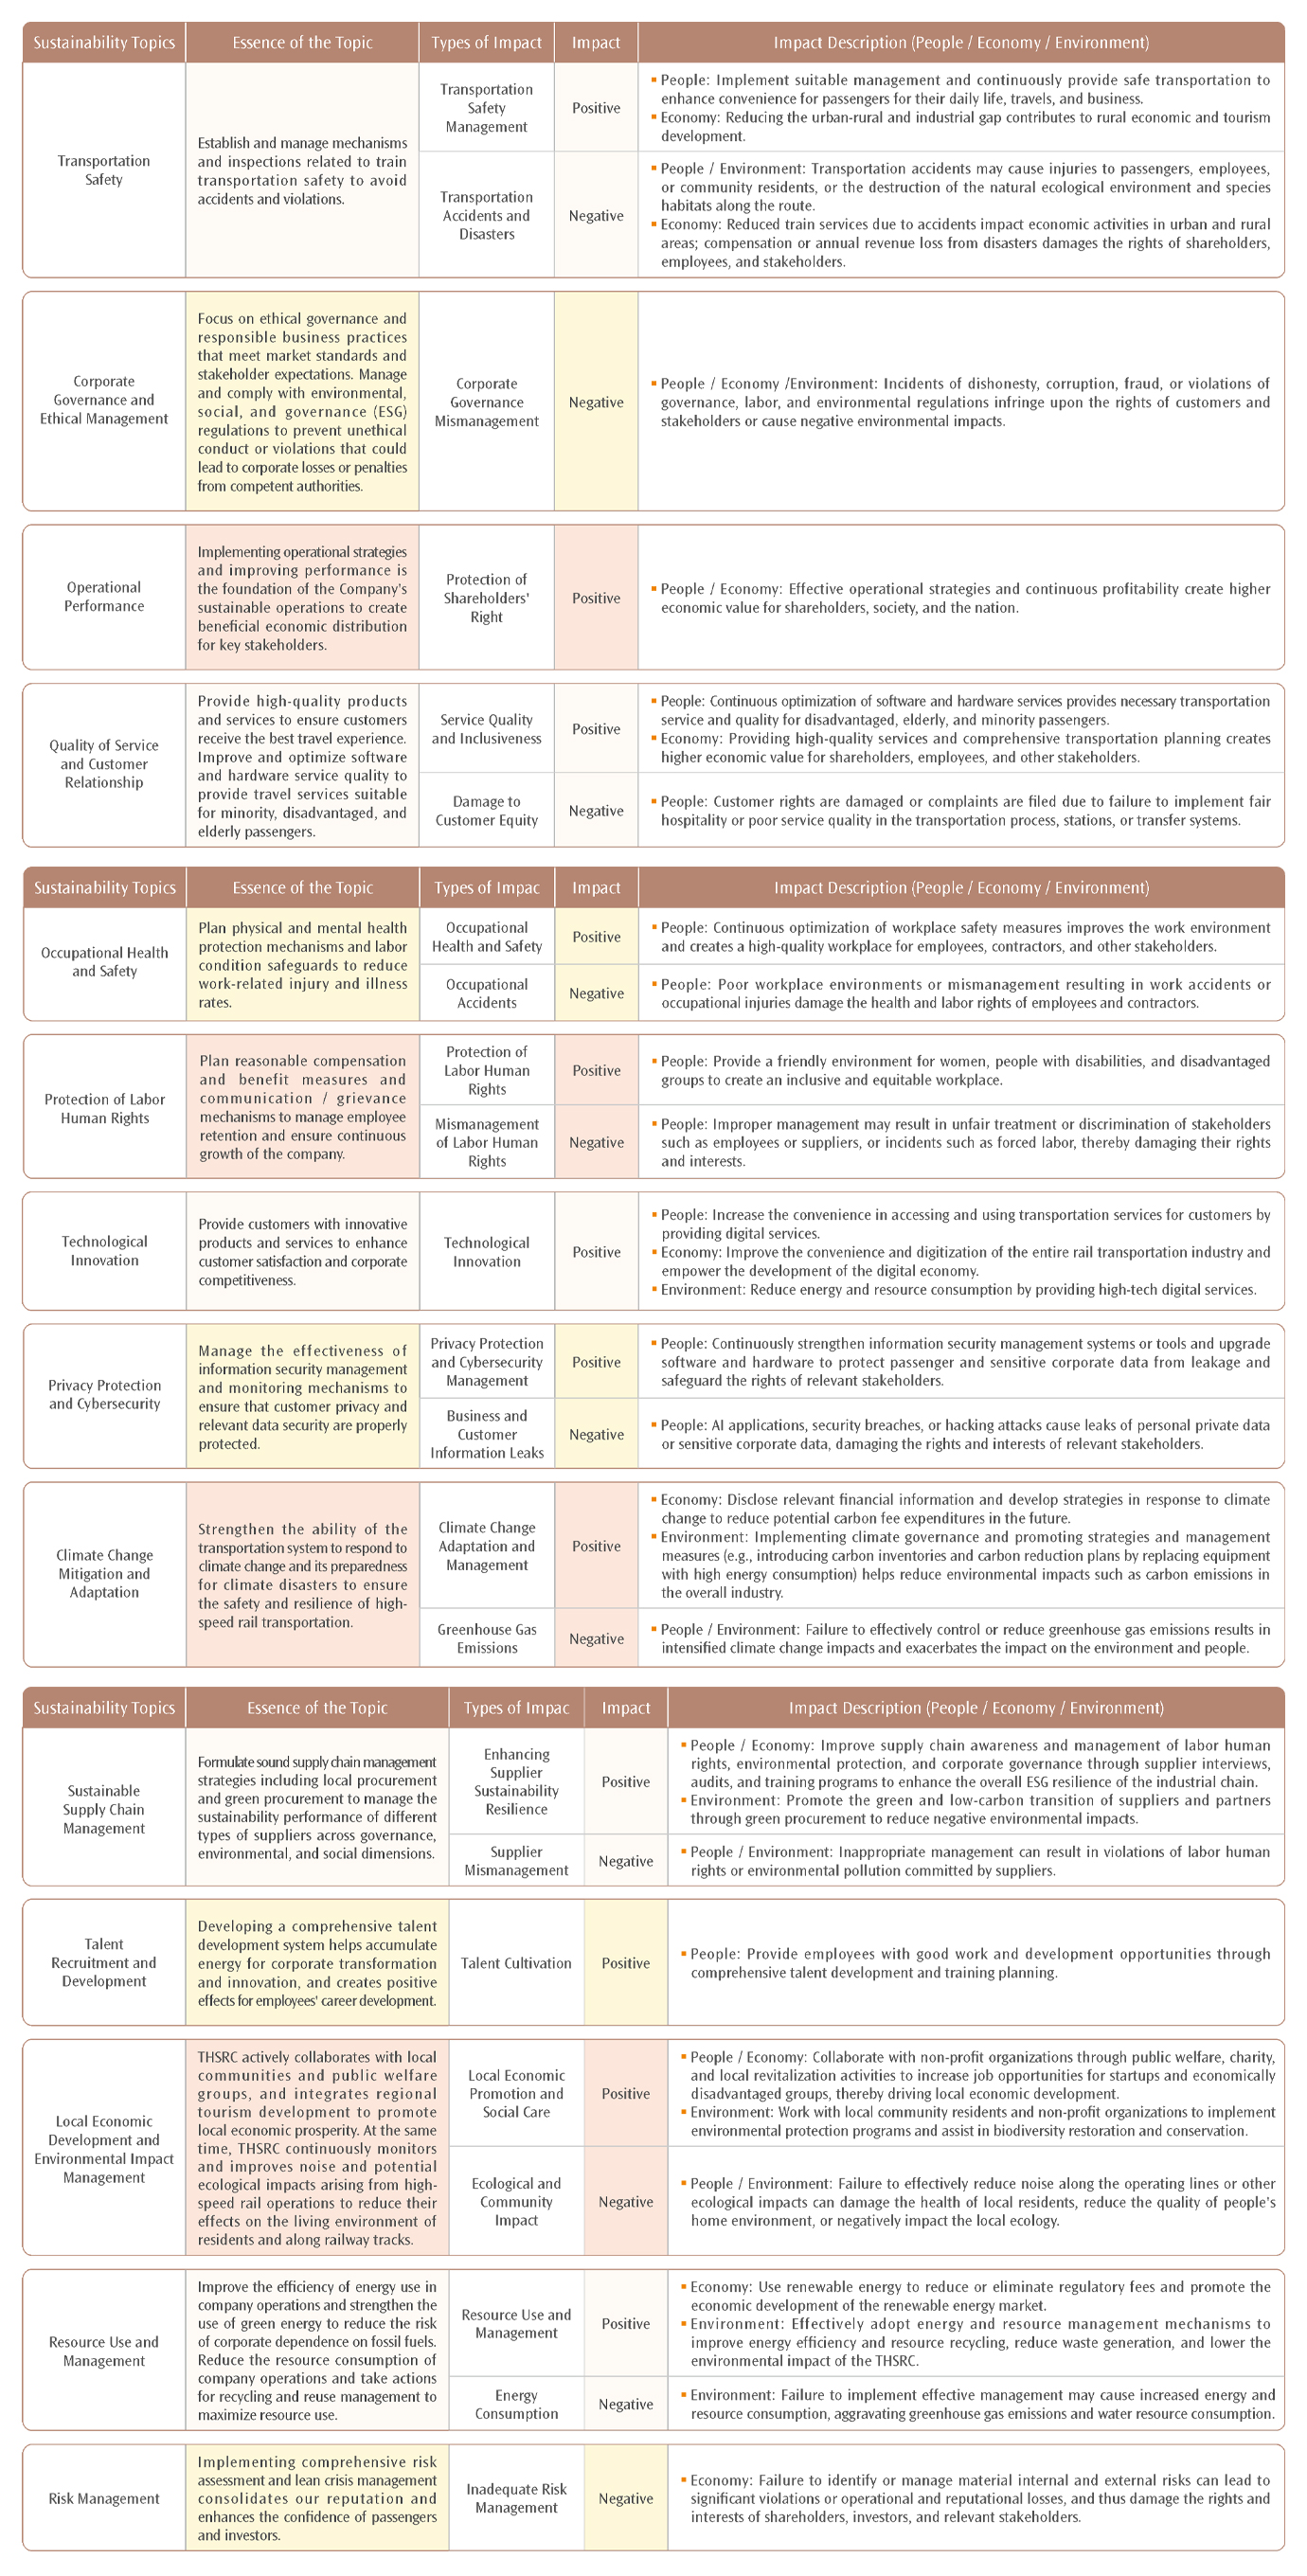
Sustainability Topics
Identifying and Prioritizing Material Sustainability Topics
THSRC continues to pay attention to the international sustainability development trend and sustainability disclosure standards and refers to the material issues of international benchmark enterprises. The THSRC Sustainability Report follows the GRI General Guidelines 2021 "GRI 3: Material Topics" issued by the Global Sustainability Standards Council to identify material sustainability topics.
In 2025, THSRC examined domestic and international sustainability regulations, ratings, and industry benchmark topics for the review of the list of sustainability topics from the previous year, along with their positive and negative impact issues and implications. THSRC appropriately adjusted the titles and descriptions of these impact implications. THSRC also referenced due diligence results and adjusted the significance and likelihood of positive and negative impacts to complete the 2025 sustainability theme priorities and impact matrix. The company evaluated the significance and materiality of the positive and negative impacts caused by sustainability topics on the economy, environment, and human rights to verify the disclosure themes and scope of the report. This process allows us to review our sustainable operation performance and address the needs of a diverse range of stakeholders. THSRC disclosed the results of the materiality assessment after they were reported to the Sustainable Development & Nomination Committee and the Board of Directors.
Assessing and Determining Material Sustainability Topics:
| Analysis Steps | Description | Stakeholder and Expert Opinion Considerations |
|---|---|---|
| Review the Sustainability Topics | In order to ensure sustainability topics keep pace with the times, respond to stakeholders' expectations, and cover the topics of focus within the railway transportation industry, THSRC, based on the list of 13 sustainability topics identified in 2024, refers to domestic and international regulations and trends, the Sustainability Accounting Standards Board (SASB), sustainability topics of the railway transportation industry identified by benchmarking companies, sustainability requirements emphasized by international sustainability assessments such as the Dow Jones Best-in-Class (DJBIC), as well as sustainability topics disclosed by international railway transportation benchmarking companies, to review the relevance of its sustainability topics. After a comprehensive review of changes in regulations and the industry, THSRC adjusted the sustainability topics as follows : 1. Corporate Governance and Ethical Management, Operational Performance THSRC made adjustments to the original sustainability topics "Corporate Governance and Operational Performance" and "Regulatory Compliance." After evaluating the Company's performance in corporate governance, ethics, and compliance, the company integrated "Regulatory Compliance" into the core scope of ethical management, renaming it "Corporate Governance and Ethical Management." THSRC also established "Operational Performance" as an independent sustainability topic. 2. Occupational Health and Safety, Protection of Labor Human Rights As occupational health and safety requires careful monitoring of workplace safety management (including the likelihood of safety accidents involving personal injury), and as the protection of labor human rights requires the establishment of human rights risk assessments, management mechanisms, and a DEI (diversity, equity, and inclusion) workplace environment, THSRC separated the original "Employee Care and Labor Protection" into two topics for evaluation. 3. Local Economic Development and Environmental Impact Management Since the primary subjects of "Local Economic Development and Human Concern" and "Ecological and Community Impact Management" are both external community residents, THSRC merged these two topics into "Local Economic Development and Environmental Impact Management" to comprehensively evaluate positive and negative impacts across environmental, economic, and human rights dimensions. 4. Risk Management As recent international geopolitical developments have increased operational risks for domestic enterprises, THSRC added "Risk Management" as a new topic. Failure to conduct regular reviews and comprehensive risk assessments, or weak crisis management capabilities, could damage corporate reputation and weaken investor confidence. |
External expert sustainability consultants review sustainability topics and advise on how to define the economic, environmental and social impacts of the issues. |
| Evaluate the Definition of Actual and Potential Impacts | Reinforce the focus on the actual and potential positive and negative impacts of each sustainability topic. In 2025, a total of 14 sustainability topics were identified, including 12 positive impacts and 11 negative impacts, with 23 positive and negative impacts identified in total. | |
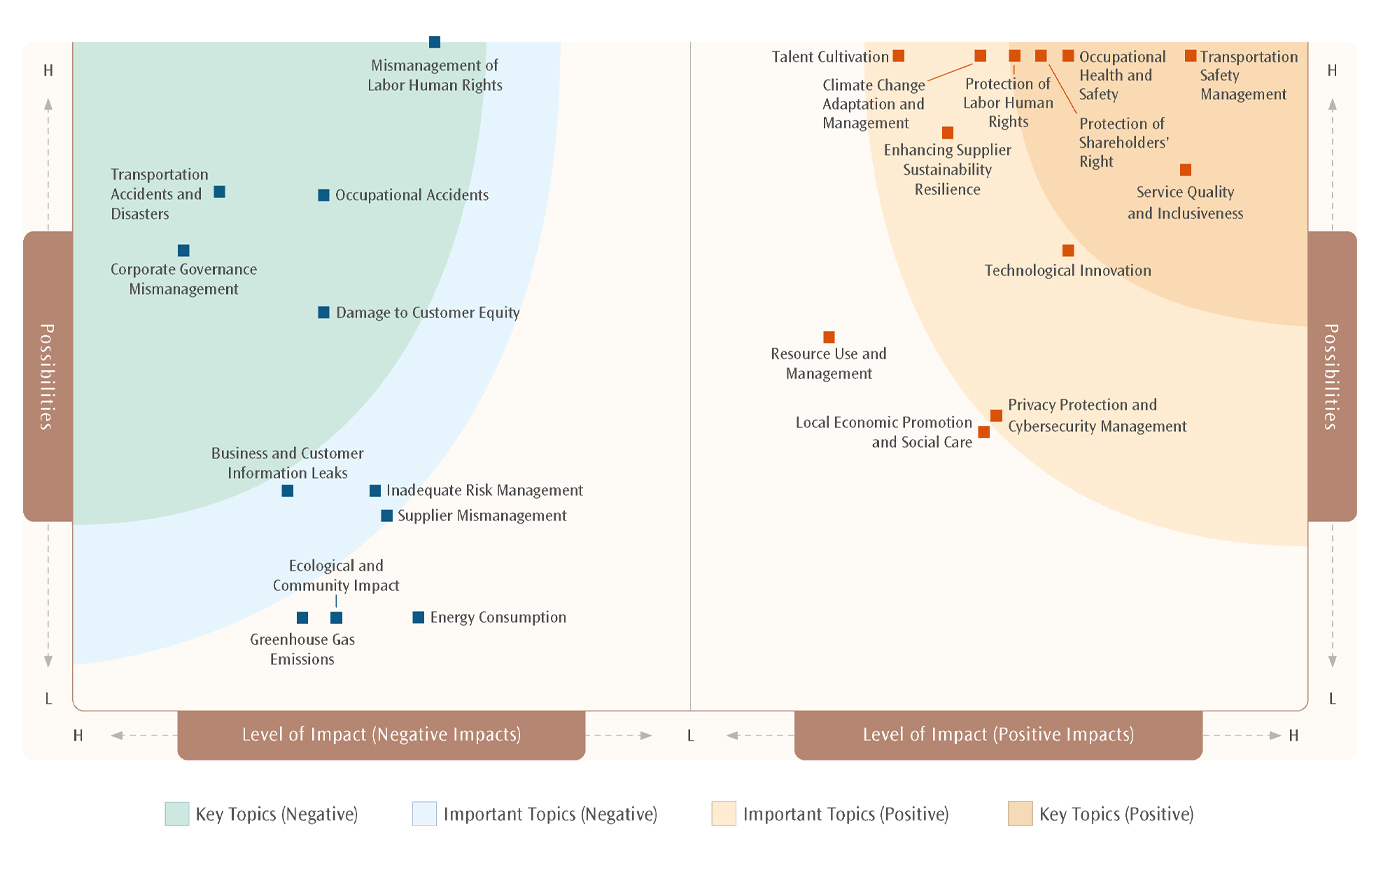
| Assess and Prioritize the Most Significance of the Impacts | THSRC distributed impact survey questionnaires to internal and external stakeholders to collect information on their materiality rankings of positive and negative impacts, which were used to adjust the level of these impacts. The impact level is the result of a comprehensive review of the significance and scale of the impact of a specific topic on the economy, environment, and people (including human rights). THSRC also incorporated feedback from internal due diligence channels to complete the assessment of the likelihood of actual and potential impacts of individual topics and adjusted the likelihood of negative impacts. | THSRC adapted stakeholder impact questionnaires, due diligence channels, and daily communication to comprehensively evaluate and adjust the materiality of sustainability issues. These adjustments include, but are not limited to: ・Travelers: Refer to customer satisfaction survey to confirm whether related rights and interests, such as privacy or other customer rights and interests. ・Employees: Refer to their opinions and complaints to confirm whether there are any workplace human rights violations or occupational safety incidents. ・Suppliers: Refer to their opinions, complaints, and audit results to determine if corporate governance, environmental pollution and labor human rights violations are involved. ・Competent authorities: THSRC adjusted the materiality of issues based on sustainability and corporate governance ratings or penalties, and policy developments (such as ESG Evaluation System, local procurement, and labor human rights protection). |
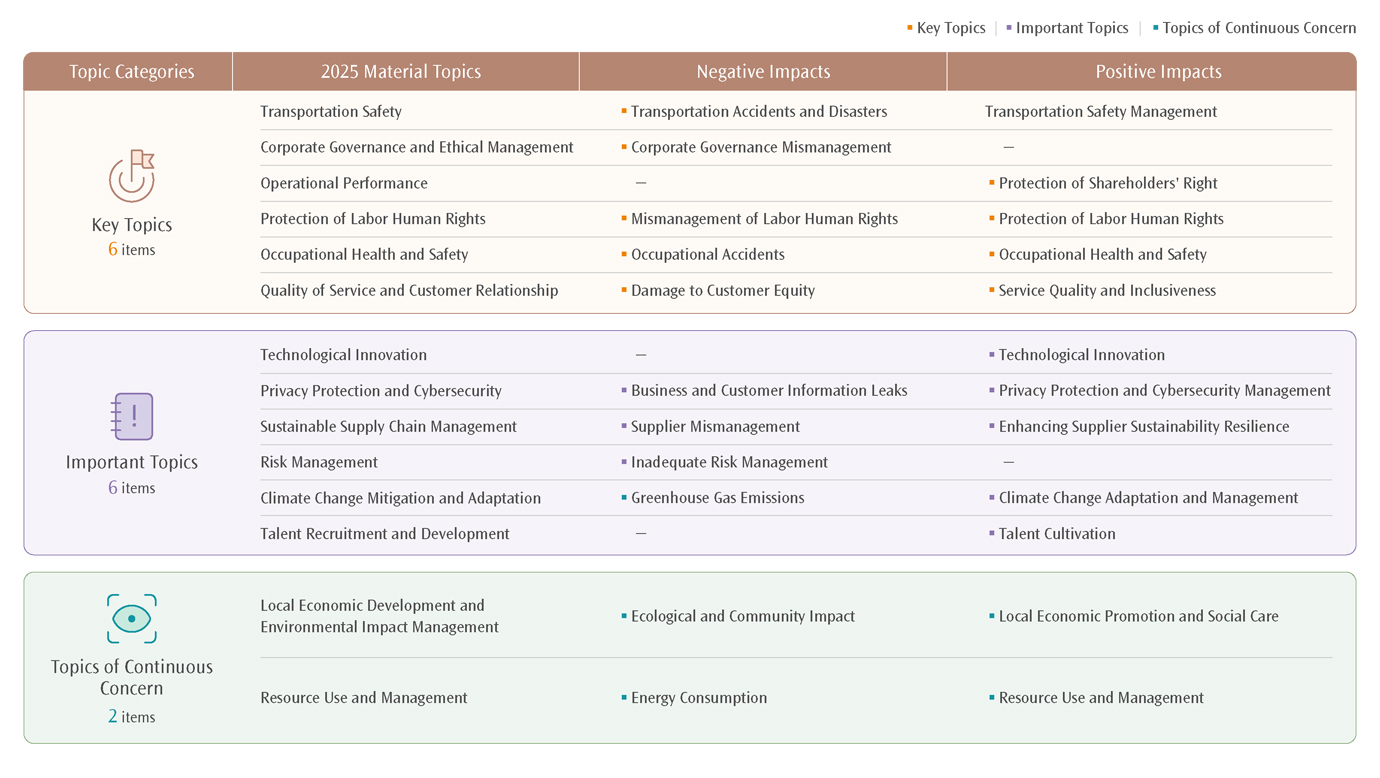
| Adjust and Determine Material Topics for Reporting | After considering the positive and negative impacts of each topic, the sustainability topics are categorized into three tiers based on the materiality assessment results, namely key topics, important topics, and topics of continuous concern. In 2025, THSRC identified 6 key topics, 6 important topics, and 2 topics of continuous concern. Among the 14 topics, "key topics" and "important topics" are selected as the primary scope of materiality disclosures in this report. In principle, topics of continuous concern are not disclosed; however, if such topics have a significant impact on material disclosures, they will still be appropriately explained and disclosed in this report. |
|
| Approval and Determine Material Topics | The results of the materiality analysis of the sustainability topics were submitted to the Sustainable Development & Nominating Committee and the Board of Directors to confirm and approve the key themes of this year's Sustainability Report. Finally, the report will be disclosed to the public. | |
Major Analysis Results and Major Thematic Matrices
Based on the results of the 2025 assessment, for positive impacts, a total of 5 impacts are key issues, 5 impacts are important issues, and 2 impacts are rated as ongoing concerns; for negative impacts, a total of 5 impacts are key issues, 3 impacts are important issues, and 3 impacts are ongoing concerns. Regardless of whether the topic is positive or negative, as long as one impact is identified as a key topic, the topic will still be identified as a key topic after consolidation.
In the materiality analysis process, THSRC has taken into account feedback from stakeholders and recommendations from external experts, and determined that sustainability topics at and above the important level should be identified as topics to be disclosed in this annual report. In 2025, there are 6 key topics, 6 important topics, and 2 topics of continuous concern, as shown in the table below.
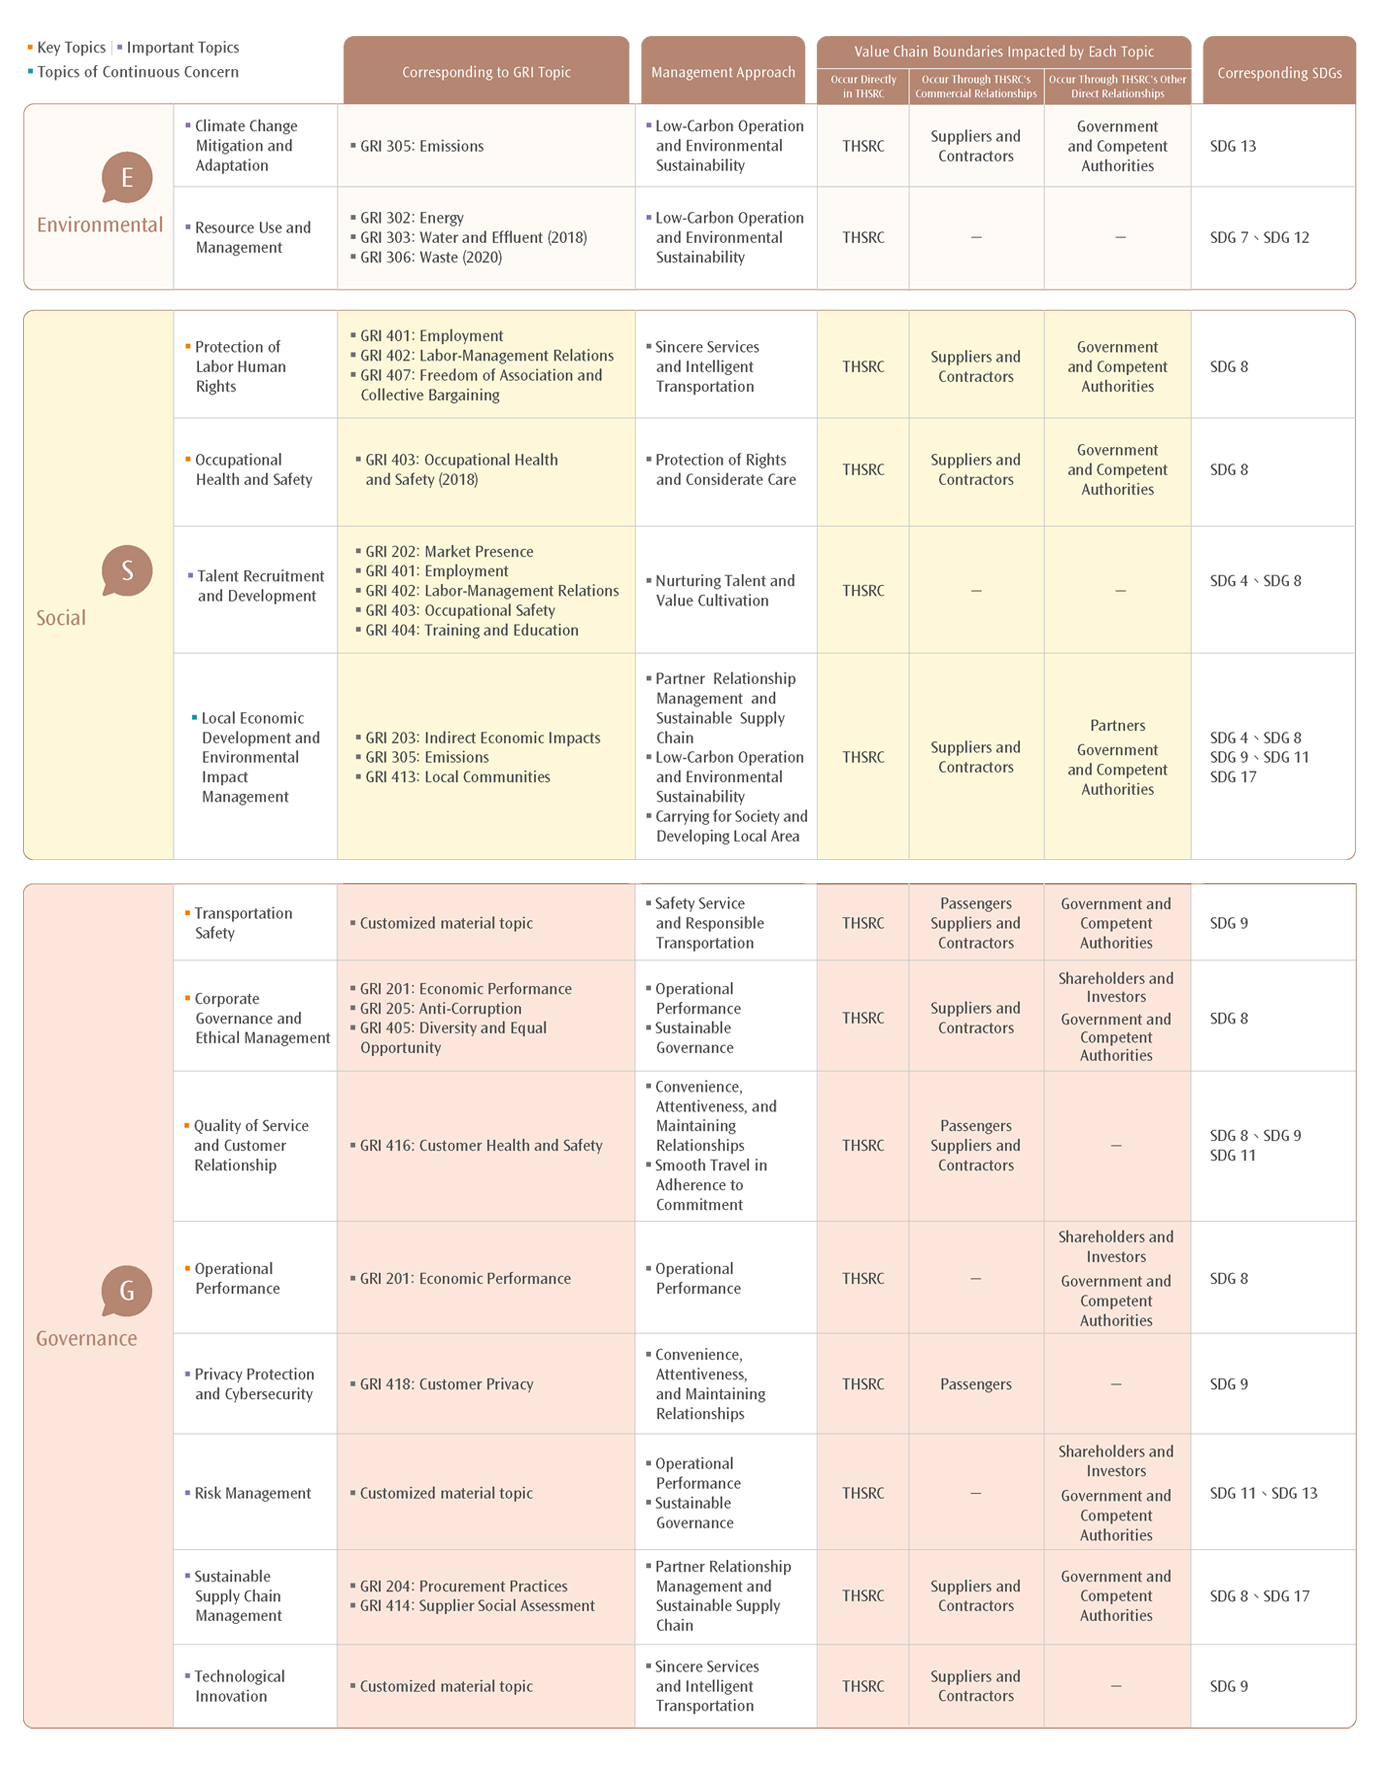
Sustainability Value Chain Impact Management
Materiality Matrix (Integration of Positive and Negative Impact)
List of Sustainability Topics and Impact Description